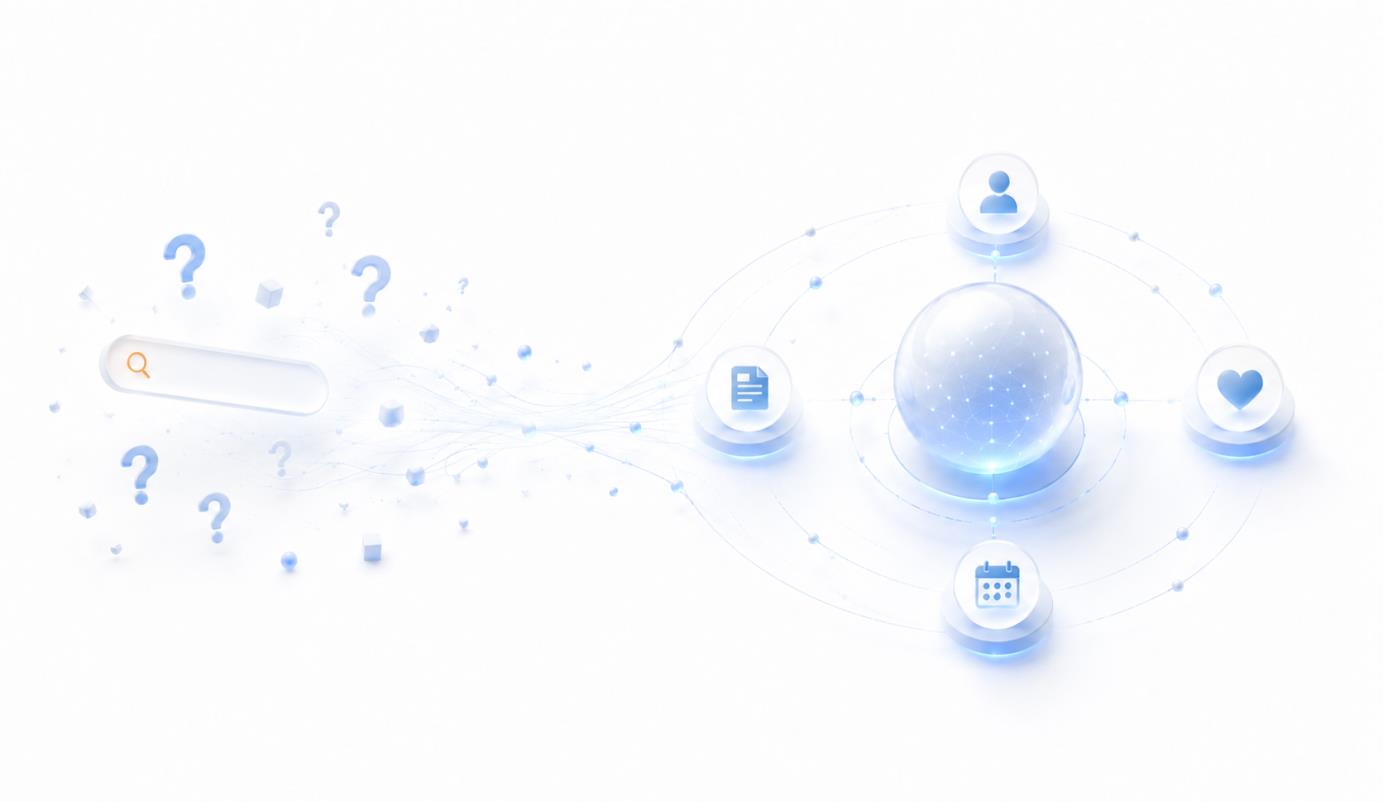
The next e-commerce moat sits before the search box.Selection won e-commerce’s first era. Fulfillment won the second. Both are becoming table stakes. Value moves upstream to whoever interprets the customer’s need before a query exists. Retail media monetizes intent. The next moat shapes it.
Retailers can bolt on AI. They cannot bolt on neutrality.Amazon can make search dramatically smarter, but it still operates inside Amazon’s catalog and economics. A retailer cannot credibly recommend that the best answer is at a competitor. AI can improve the old journey. It does not automatically create a neutral context layer.
The next moat is a new architecture, not a better interface.Behavioral data records what customers did. A context architecture learns what they need, guides them to a trusted solution, and records whether the solution worked. Each verified outcome deepens context and trust. The metric shifts from time-to-cart to time-to-trusted-solution.
Since the modern era of consumer e-commerce began in the mid-1990s, the search box has been treated as the start of the customer journey. In reality, it appears only after the customer has done the hardest work: turning a real-world problem into a searchable query. AI can finally take on that context burden and move commerce upstream. The company that earns trust at that context layer will own the next moat.
Why Search Falls Short
A father in San Francisco received an IEP, an Individualized Education Program, for his five-year-old son, recently diagnosed with autism. Kindergarten was approaching.
He opened Amazon. The search bar blinked.
And the architecture assumed he already knew what he did not know.
What should he type? “Sensory toys”? “Autism school supplies”? “Weighted blanket”? “Noise-reduction headphones”?
A marketplace search for “sensory toys” returned more than 30,000 results. The first page showed 48 product tiles, roughly one-third of which were sponsored. The page offered star ratings, delivery promises, coupons, and “Best Seller” badges. Those signals were not useless. But they were product recommendations shaped by marketplace economics: ratings, delivery promises, sponsored placement, past behavior, and conversion likelihood. They were not solutions. Amazon knew the query and may have had purchase-history signals from the account. But it did not know the need, the life context, or the outcome the father was trying to achieve. It knew almost nothing about the child he was shopping for, the IEP he was trying to support, or the question he was actually asking: “What does my child need to succeed?”
So the father spent hours assembling the answer himself: reading the IEP, reviewing therapy notes, talking to specialists, joining parent groups, testing general AI chatbots, and comparing products across marketplaces before the conventional e-commerce journey even began. The recommendations improved only when he supplied richer context. That is precisely the asymmetry: customers with time, fluency, and confidence can translate context into better queries. Everyone else carries the burden alone.
Call this the context burden: the cognitive, emotional, and logistical work customers must do before their intent becomes searchable. E-commerce did not eliminate that burden. It pushed it upstream, outside the interface, and asked the customer to carry it alone.
That upstream gap is where the next e-commerce moat will be built: not in showing more options or moving boxes faster, but in turning a customer’s situation into a trusted solution before a query crystallizes.
Search still works for replenishment and known-item purchases. But those are the cases where the customer has already done the hardest work. The broader question is where search fails hardest — and whether solving the problem upstream is valuable enough to create a new moat.
The issue is not niche. More than one in four U.S. children had a special health care need in 2022–2023, and nearly one in four U.S. adults is a caregiver.1 The same pattern appears in ordinary retail.
U.S. retail returns remain a massive profit leak, projected to reach nearly $850 billion in 2025, with an estimated 19.3% of online sales returned.2 A meaningful share of that waste is not a delivery problem. It is an intent-articulation problem: customers are asked to commit to a product before they have enough context to know whether it will work. The context burden does not disappear at checkout. It comes back as a return.
Outside simple replenishment, much of shopping is more complex than the search box admits. A child’s diagnosis, post-surgical recovery, elder care, a new food allergy, a dorm room, a home office, or even replacing a product used for years all require judgment before query. The challenge is not moving faster from query to cart. It is moving from ambiguity to confidence — from problem to trusted solution.
The problem is not lack of information. It is lack of orchestration.
That is the core design flaw: search does not eliminate the cognitive labor of shopping. It hides that labor outside the interface and asks the customer to solve it alone.
The Three Eras of E-Commerce Moats
The first moat was selection. Amazon’s “Everything Store” strategy turned online retail into the endless aisle. Abundance became searchable, and selection itself became a moat.
The second moat was fulfillment and habit. Amazon added a vast delivery network, then locked in behavior through programs like Prime and Subscribe & Save. Those capabilities were expensive and low-margin at the retail layer, but they strengthened the flywheel: more customers, more sellers, greater scale, better economics. Retail media became the high-margin profit pool made possible by winning the earlier races for selection and fulfillment — and the demand habit those moats created.
As broad selection and fast delivery become table stakes, the next durable moat is contextual intelligence: the ability to understand a customer’s situation and translate it into trusted, personalized, retailer-agnostic solutions before the customer knows what to search for.
Each era has moved value upstream. Selection answered, “What can I find?” Fulfillment answered, “How fast can I get it?” Contextual intelligence answers the hardest question: “What do I actually need?” The new moat does not destroy the old ones. Selection and fulfillment remain hard, capital-intensive, and scale-dependent. But as they become prerequisites among the leaders, the highest-margin control point moves upstream to the context layer that shapes demand before the transaction begins.
That shift matters economically. Amazon’s advertising services revenue reached $68.6 billion in 2025.3 Retail media monetizes expressed intent: the moment a customer is already query-ready and close to purchase. Contextual commerce monetizes something earlier: intent formation — the moment a customer is still deciding what problem they are solving, which products qualify, and which destination deserves the order.
Even the search layer itself is leaking value. Google Cloud-commissioned Harris Poll research estimates that search abandonment costs retailers more than $2 trillion annually worldwide.4 That is the visible failure, after the customer has reached the search box. The larger, less measured failure sits just before it: customers with urgency and willingness to spend who cannot yet translate a real-world problem into a product query. If that decision moves upstream, the margin pool moves upstream with it.
The early evidence suggests this is no longer theoretical. Adobe Analytics reports that AI-driven traffic to U.S. retail sites rose 393% year over year in Q1 2026, and AI-referred traffic moved from converting 38% worse than non-AI traffic in March 2025 to 42% better in March 2026 — an 80-percentage-point swing in one year.5 This is not just traffic moving from one referral source to another. It is demand beginning to form outside the retailer’s own interface.
The web is already moving from search engines to answer engines. E-commerce will make the parallel move from product search to solution discovery. Search retrieves options. Contextual commerce interprets the problem, clarifies the need, and routes demand to the right products, retailers, or providers.
As selection and delivery speed become table stakes, product information becomes less scarce than trusted interpretation. The retailer that sells or fulfills the order may no longer capture the most valuable part of the journey. The new high-margin control point is the trusted context layer that clarifies what should be bought before the transaction begins.
Behavioral Data’s Blind Spot
The incumbent e-commerce moat is anchored in behavioral data: what customers searched, clicked, carted, purchased, returned, and reviewed. That data is extraordinarily powerful. It predicts what a customer may buy next based on what the customer bought before.
But behavioral data has a structural blind spot. It knows what you did. It does not always know what you need.
A parent whose child has just received an autism diagnosis has no purchase history that reliably predicts sensory headphones, weighted lap pads, visual schedules, or adaptive clothing. Those needs are shaped by situational context — health events, family dynamics, educational requirements, budget, timing, emotional load — variables that live outside a purchase-history table.
Amazon’s own evolution illustrates the point. Amazon says Rufus helped more than 300 million customers in 2025 research, compare, and buy products; in 2026, it brought Rufus’s product expertise into Alexa for Shopping, a more personalized, agentic assistant.6 That confirms the architectural shift. But even the best assistant inside a retailer’s ecosystem remains constrained by that retailer’s catalog, permissions, and incentives. Better search is not the same as a trusted context layer.
Instacart shows the same pattern from another angle. Its Smart Shop system uses generative AI to personalize grocery discovery around dietary preferences and household context; the company describes the old experience of shopping for dietary needs as a “scavenger hunt.” Later in 2025, Instacart launched an app inside ChatGPT with embedded shopping, allowing users to move from a meal-planning conversation to a grocery order without switching apps.78 These moves do not yet solve trusted solution discovery. But they show that the interface, checkout flow, and economics of e-commerce are being rewired.
Why Incumbents Cannot Just Add Context
If contextual intelligence is valuable, why can’t Amazon, Google, or Walmart simply add context to their existing shopping interfaces? They can add AI and conversational assistants. Many already have. Andy Jassy has warned that AI could make the retail interface “substantially different over time.” Walmart’s Doug McMillon was more direct: “For many years now, e-commerce shopping experiences have consisted of a search bar and a long list of item responses. That is about to change.”9
But the hard part is not adding AI capability. It is escaping the architecture of search — and the incentives built around it. Three constraints matter most.
The first is architecture. Most incumbent systems are built around search, product detail pages, conversion, retail media, and fulfillment. AI can improve each layer. But that is optimization, not reinvention. It makes the journey smarter after the customer asks; it does not own the decisive moment when need becomes intent.
The second is trust. A parent may share an IEP or therapy note with a platform built around privacy and the family’s best interest. That same parent may be far less willing to share sensitive context with a retailer whose model depends on monetizing sponsored placement. This skepticism is not abstract: Pew Research Center found that 70% of Americans who have heard of AI have little or no trust in companies to make responsible decisions about AI use, and 81% think companies will use collected information in ways people are not comfortable with.10
The third is neutrality. Amazon cannot credibly recommend that the best product is at Walmart, and vice versa. That creates an opening for a trusted layer that asks not, “What can I sell from my shelf?” but, “Which solution best fits this situation?”
Horizontal AI assistants — ChatGPT, Perplexity, Gemini — may be more neutral, but their shopping features sit inside general-purpose interfaces. The early evidence suggests they are powerful research engines but have not yet become transaction owners; OpenAI’s own product-discovery announcement says it is moving away from a standalone Instant Checkout experience and prioritizing better shopping discovery while allowing merchants to use their own checkout experiences.11 A general chatbot can start the conversation. It does not yet own the outcome. Owning the outcome requires commerce-native context: inventory, loyalty, returns, preferences, fulfillment, and post-purchase data.
That is why the economic model matters. Search advertising monetized expressed intent. Social advertising monetized attention and influence. Retail media monetized proximity to purchase. A trusted context layer would sit one step earlier: where intent is interpreted and the destination is chosen. If the customer is asking, “What solution fits my situation?” the most valuable layer is the one the customer trusts to interpret the need.
Where Contextual Commerce Starts
Contextual commerce applies wherever the customer is solving for an outcome, not replenishing a known item. Care-navigation is a strong beachhead because it is a category where customers need intelligent help the most, receive it the least, and have the strongest reason to share context when trust is earned.
Families navigating special care needs already spend hours assembling fragmented context across schools, therapists, doctors, forums, and retailers. That unpaid labor is the business case: high urgency, low confidence, costly mistakes, and a willingness to pay for trusted reduction of uncertainty. A platform that converts those fragments into a trusted starter kit creates an immediate value exchange. The first solved problem earns trust. Trust enables deeper context. Deeper context produces better recommendations. Over time, the record of what was kept, returned, recommended by specialists, or actually helped creates a trust flywheel — one that generic AI and retailer-bound engines will struggle to imitate.
But the pattern extends well beyond care. Consider the allergy-safe pantry. A family managing a new nut allergy is not looking for one product. It is trying to understand trusted brands, ingredient rules, school-snack policies, restaurant constraints, and replacement products. Today, that work is scattered across doctors’ guidance, product labels, parent forums, and trial and error. A context layer that turns that fragmented burden into a verified shopping list does more than save time. It replaces anxiety with confidence.
Care-navigation is the proof point, not the perimeter. The broader shift is from product search to trusted solution discovery.
Measuring the Context Moat
The danger is not that retailers are ignoring AI. The danger is the search-improvement trap: using powerful new tools to improve an interface still tethered to the search box, while someone else earns the customer’s trust and context before the search begins. Once that upstream relationship forms, the retailer may still fulfill the order, but it no longer owns the moment when the need becomes clear.
The signal to watch is not the sophistication of the AI model. It is the architecture of the trust relationship. A company that earns data by solving specific, urgent, high-context problems — and documents what actually helped — is building a moat that keyword search and generic recommendation engines cannot easily copy.
A customer journey is most vulnerable to upstream capture when the customer begins with ambiguity, the context sits outside purchase history, the wrong choice is costly, trust affects the recommendation, and outcomes can be measured after the transaction. Apply the test to home improvement. A homeowner recovering from storm damage is highly vulnerable: ambiguous scope, little useful purchase history, expensive mistakes, high trust sensitivity, and a measurable outcome. A customer reordering furnace filters is less vulnerable: the need is known, the product is repeatable, and the cost of being wrong is lower. The first journey is broken in ways traditional search does not solve. The second is less broken — and gains less from leaving traditional search and replenishment flows.
The context moat has five operating layers: situational context, trusted interpretation, solution discovery, neutral curation, and the what-worked loop. Traditional e-commerce asks, “What did the customer buy?” Contextual commerce asks the more valuable question: “What outcome did the customer need — and did the solution work?”
That requires a new metric. Search-era commerce optimized for time-to-cart: how quickly a customer moved from query to purchase. Contextual commerce should optimize for time-to-trusted-solution: how quickly a customer moves from an ambiguous problem to a confident, validated outcome. The first measures transaction efficiency. The second measures whether the platform is earning trust before the transaction exists. No major retailer treats that as the governing metric. That is the opening.
The Next Moat
For nearly 30 years, the search box has been e-commerce’s front door. But it was never the true beginning of the customer journey. It was the moment after the customer had already done the hardest work: translating an ambiguous real-world problem into a product query.
AI changes that. It allows commerce to move upstream — before the query, before the cart, before the ad auction — to the moment when a customer’s need is still forming and trust matters most.
The company that wins this layer will not need the biggest catalog or the fastest truck. Those will still matter, but they will no longer be the highest-margin control point. The prize will be owning the context layer where need becomes intent, intent becomes a trusted solution, and the value pool moves upstream.
Before the search. That is where the moat is built.
Sid Breja is the founder of Moat Vision and a former finance and strategy executive at Amazon, Uber, eBay, Capital One, and JUUL Labs. His work spans profitable growth, marketplace economics, capital allocation, M&A, and competitive advantage.